Speak with a licensed insurance agent

1-855-454-9051

TTY user 711 Mon-Fri : 8am-9pm EST

Medicare Part B Premium 2027

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated September 15, 2026

If you are trying to budget for next year, here is the short version: the 2027 Medicare Part B premium has not been set. The most widely cited estimate is $209.50 per month, which comes from the 2026 Medicare Trustees Report published in June 2026. That would be a rise of about 3.25% from the confirmed 2026 premium of $202.90.

That number is a projection, not a rate. CMS sets the official Part B premium, deductible and income brackets each fall, and has historically published them in November. Until that announcement lands, every 2027 figure you see anywhere — including on this page — is an estimate.

Below is what is actually confirmed, what is still being projected, how far off past projections have been, and the one common way a Medicare beneficiary can reduce what they pay.

Nothing about 2027 is official yet

The 2027 Part B premium, the 2027 deductible and the 2027 IRMAA income thresholds are all unannounced as of today. Treat the figures on this page as planning estimates and check back after the CMS announcement, which is expected in November 2026.
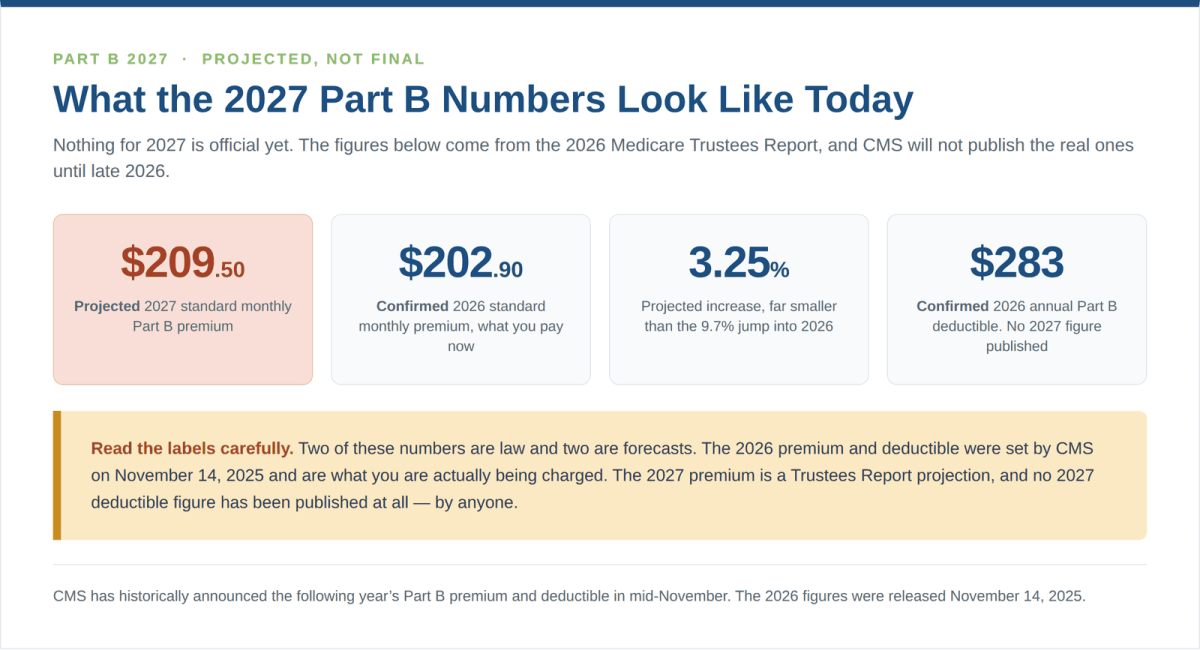
Projected 2027 Medicare Part B premium of $209.50 per month compared with the confirmed 2026 premium of $202.90

What the 2027 Part B Premium Is Projected to Be

The 2026 Medicare Trustees Report projects a standard 2027 Part B premium of $209.50 per month. That is a monthly increase of roughly $6.60 over the current $202.90, or about 3.25%.

One detail that tends to get lost: this projection was revised downward. The previous year’s Trustees Report had projected a 2027 premium of $218.60. Lower-than-expected Medicare spending through the first half of 2026 brought the estimate down. That is unusual, and it is a genuinely good sign for beneficiaries — but it is not a guarantee.

Some independent analysts think the final figure will land higher than the Trustees baseline, in the range of roughly $215 to $219 a month, pointing out that the Trustees have underestimated the final CMS number before. Both views are worth knowing, and neither is official.

Figure 2026 (confirmed) 2027 (projected)
$Standard monthly premium $202.90 About $209.50
Annual deductible $283 Not yet projected by CMS
Year-over-year increase $17.90 (about 9.7%) About $6.60 (about 3.25%)
Part A hospital deductible $1,736 Not yet announced
Status Final — announced November 14, 2025 Estimate — CMS expected to confirm in November 2026

Compare Medicare Plans for 2027

Six Years of Part B Increases, and the One Year It Fell

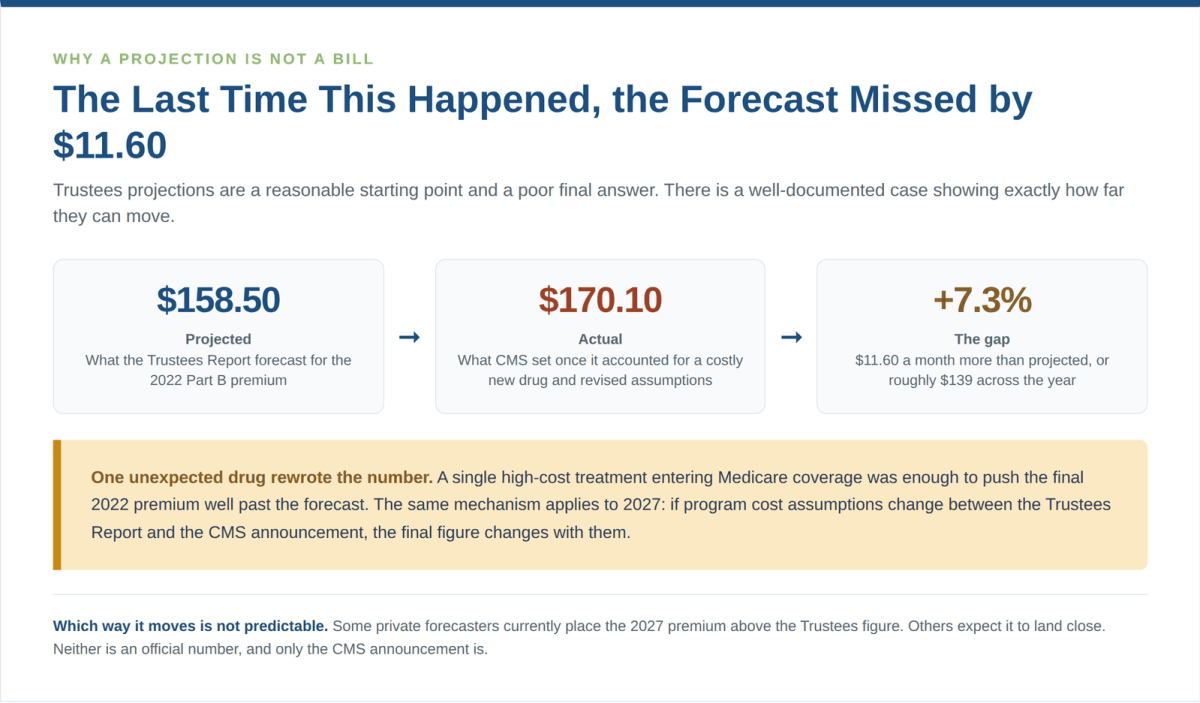
Medicare Part B premium projections compared with the actual CMS rates showing how far past Trustees estimates have missed

Context helps here. The standard Part B premium has gone up in every year since 2020 except one, rising from $144.60 to $202.90 — a 40% increase over six years.

Year Standard monthly premium Change
2020 $144.60
2021 $148.50 Up $3.90
2022 $170.10 Up $21.60
2023 $164.90 DOWN $5.20
2024 $174.70 Up $9.80
2025 $185.00 Up $10.30
2026 $202.90 Up $17.90
2027 About $209.50 PROJECTED

The 2023 decrease is the exception that explains a lot. The 2022 premium had been set unusually high partly to build a reserve for an expensive new Alzheimer’s drug. When that spending did not materialize, the 2023 premium came back down. It is a useful reminder that the Part B premium is driven by projected program spending, and projections can miss in both directions.

The large 2026 jump of $17.90 was attributed by CMS mainly to projected price changes and expected increases in how much care people use. CMS also noted that without action taken on spending in one specific category, the increase would have been roughly $11 a month higher.

The 2027 Part B Deductible

The annual Part B deductible for 2026 is $283, up $26 from $257 in 2025. This is what you pay out of pocket for Part B services each year before Medicare starts paying its share.

CMS has not projected a 2027 deductible, and the Trustees Report does not publish one either. Historically the deductible moves in step with the percentage increase in the Part B premium. Applying the projected 3.25% premium increase to the current $283 would put the 2027 deductible at roughly $292. Some other published forecasts run higher, closer to $310.

Why you will see different deductible estimates

Different sources use different methods. Some apply the projected premium percentage, some use separate actuarial modeling. That is why published 2027 deductible estimates range from roughly $292 to roughly $310. We would rather show you the spread than pretend there is one settled answer.

IRMAA in 2027: What Higher Earners Could Pay

If your income is above a certain level, you pay an Income-Related Monthly Adjustment Amount, or IRMAA, on top of the standard Part B premium. It affects roughly 8% of people with Part B.

Two things matter for 2027. First, IRMAA uses a two-year lookback, so your 2027 bracket will be determined by the income reported on your 2025 tax return. Second, the 2027 income thresholds have not been published. Some analysts estimate the first tier will start near $112,000 for single filers and $224,000 for joint filers, but those are estimates, not official figures.

Here are the confirmed 2026 brackets, which are the best available guide to what the 2027 structure will look like:

Individual return (2024 income) Joint return (2024 income) Total 2026 monthly premium
$109,000 or less $218,000 or less $202.90
Above $109,000 up to $137,000 Above $218,000 up to $274,000 $284.10
Above $137,000 up to $171,000 Above $274,000 up to $342,000 $405.80
Above $171,000 up to $205,000 Above $342,000 up to $410,000 $527.50
Above $205,000 and below $500,000 Above $410,000 and below $750,000 $649.20
$500,000 or more $750,000 or more $689.90

There is a separate Part D IRMAA surcharge at the same income tiers, which in 2026 ranges from $14.50 to $91.00 per month. If a life event has reduced your income since the tax year being used, you can ask Social Security to reconsider your bracket.

The Giveback Benefit: Lowering What You Actually Pay

You cannot negotiate the Part B premium. It is set by CMS and, for most people, deducted straight out of the monthly Social Security payment. There is, however, one common way to reduce what actually leaves your account: a Medicare Advantage plan with a Part B premium reduction, usually marketed as a giveback.

1How it works  ·  Less withheld, bigger deposit

The plan credits part of your Part B premium back to you. Less is withheld from your Social Security payment, so the amount deposited in your account goes up by that amount each month.

2Amounts vary by plan and county  ·  A few dollars to the full premium

Credits range from a few dollars a month up to the full standard premium, depending entirely on the plan and where you live. Not every ZIP code has a giveback plan available, and a plan offering one this year may not offer it next year. Amounts for 2027 are not published yet.

3Do not choose a plan on the giveback alone  ·  The expensive mistake

A giveback reduces your Part B premium. It does not eliminate it, and you must stay enrolled in Part B. More importantly, a plan with a generous giveback can easily cost you more overall through a narrower network, weaker drug coverage or a higher out-of-pocket maximum. Compare the whole plan, not one line item.

If you want to see how the rest of the plan landscape is shaping up, our guides to Medicare Advantage plans for 2027 and the best Medicare Advantage plans for 2027 cover what is expected to change, and our 2027 costs and benefits by carrier breakdown compares the major national carriers side by side.

Find & Compare Plans Online

Speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

What This Means for Your 2027 Coverage Decision

The Part B premium is the same whether you stay on Original Medicare or enroll in a Medicare Advantage plan. Everyone in Part B pays it. What changes between those paths is everything layered on top: what you pay for a hospital stay, what your drugs cost, whether there is a cap on your annual spending, and whether any of that premium comes back to you.

For 2026, Medicare Advantage plans carry a maximum out-of-pocket limit of $9,250 for in-network care. Original Medicare has no annual out-of-pocket cap at all. That difference matters far more to most budgets than a $6.60 swing in the monthly premium.

The Annual Enrollment Period runs October 15 through December 7, 2026 for coverage starting January 1, 2027. If you want to work through the tradeoffs before then, start with Original Medicare vs Medicare Advantage for 2027 or, if you are weighing a supplement instead, Medigap vs Medicare Advantage. If your current plan is not being renewed, are Medicare Advantage plans going away in 2027 explains your options and the special enrollment rights that come with a plan exit.

The Part B premium is identical in every state, but what you get on top of it is not. Plan availability, networks, and giveback amounts are set county by county, which is why the same premium buys very different coverage depending on where you live. Our state guides show how that plays out, starting with Medicare Advantage plans in Georgia.

When the Official 2027 Numbers Arrive

Two separate announcements drive what you will actually pay, and they come from two different agencies on two different schedules.

1Social Security announces the COLA  ·  October 2026

The Social Security Administration publishes the 2027 cost-of-living adjustment. This determines how much your benefit rises before the Part B premium is deducted.

2CMS announces the Part B figures  ·  November 2026

CMS publishes the official 2027 Part B premium, the annual deductible and the full IRMAA bracket table. The 2026 figures were released on November 14, 2025, which is a reasonable guide to timing.

The hold harmless protection

Most people having their premium deducted from a Social Security check cannot have that check reduced in dollar terms by a Part B increase. In practice, if the Part B increase would exceed your COLA, your premium increase is limited.

It does not apply to everyone. People new to Medicare, those paying IRMAA, those not having premiums deducted from Social Security, and people enrolled in Medicaid are all outside the protection.

We will update this page as soon as CMS publishes the confirmed 2027 figures. Until then, budget with the projection and leave yourself a little room above it.

Compare Medicare Plans for 2027

Frequently Asked Questions About the 2027 Medicare Part B Premium

  How much will the Medicare Part B premium be in 2027?

The 2026 Medicare Trustees Report projects a standard 2027 Part B premium of about $209.50 per month, up from the confirmed 2026 premium of $202.90. That is an increase of roughly $6.60 a month, or about 3.25%. Some independent analysts expect the final number to land higher, in the range of $215 to $219. CMS has not announced the official 2027 premium and is expected to do so in November 2026.

  What is the Medicare Part B deductible for 2027?

It has not been announced. The 2026 annual Part B deductible is $283. Because the deductible has historically moved in line with the percentage increase in the Part B premium, applying the projected 3.25% increase would put the 2027 deductible near $292. Other published forecasts estimate closer to $310. CMS is expected to confirm the actual figure in November 2026.

  What are the income limits for Medicare premiums in 2027?

The 2027 IRMAA income thresholds have not been published. For 2026, the standard premium applies to individuals with income of $109,000 or less and joint filers at $218,000 or less, with five higher brackets above that. Some analysts estimate the 2027 first tier will begin near $112,000 for individuals and $224,000 for joint filers, but those are projections. Your 2027 bracket will be based on the income reported on your 2025 tax return.

  Is Medicare Part B free at age 65?

No. Unlike Part A, which most people receive premium-free based on their work history, Part B carries a monthly premium at every age. The standard premium in 2026 is $202.90 a month, and higher earners pay more through IRMAA. Some people qualify for state assistance through a Medicare Savings Program that can cover the Part B premium, and some Medicare Advantage plans credit a portion of it back.

  Does everyone pay the same Medicare Part B premium?

No. About 92% of people with Part B pay the standard premium, which is $202.90 in 2026. The remaining 8% pay an income-related surcharge on top of it, ranging from $284.10 to $689.90 a month in 2026 depending on income. A smaller group pays less than the standard amount because of the hold harmless provision or because a Medicare Savings Program or a Medicare Advantage giveback benefit covers part of the cost.

  Can a Medicare Advantage plan lower my Part B premium?

Some can. A Medicare Advantage plan with a Part B premium reduction, often called a giveback, credits part of your premium back so that less is withheld from your Social Security payment. Credits range from a few dollars a month up to the full standard premium depending on the plan and county, and these plans are not available everywhere. You must remain enrolled in Part B either way, and 2027 giveback amounts are not published yet.

  When will CMS announce the official 2027 Medicare Part B premium?

CMS has historically announced the following year’s Part B premium, deductible and IRMAA brackets in November. The 2026 figures were published on November 14, 2025, so the 2027 figures are expected in November 2026. Separately, the Social Security Administration announces the annual cost-of-living adjustment in October.

  Why did the projected 2027 Part B premium go down from earlier estimates?

The previous Trustees Report had projected a 2027 premium of $218.60. The 2026 report revised that down to about $209.50 after Medicare spending through the first half of 2026 came in lower than expected, along with changes to utilization assumptions. Downward revisions are uncommon, and the final CMS figure has exceeded the Trustees projection in past years, so the estimate should still be treated as a floor rather than a ceiling.

Have Questions?

Speak with a licensed insurance agent

1-855-454-9051

TTY users 711

Mon-Fri: 8am-9pm ET

Find & Compare Plans Online

Speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

ZRN Health & Financial Services, LLC, a Texas limited liability company