There is no universal answer here, and anyone who gives you one without asking about your doctors, your prescriptions and your budget is selling rather than advising.
Original Medicare tends to fit you if
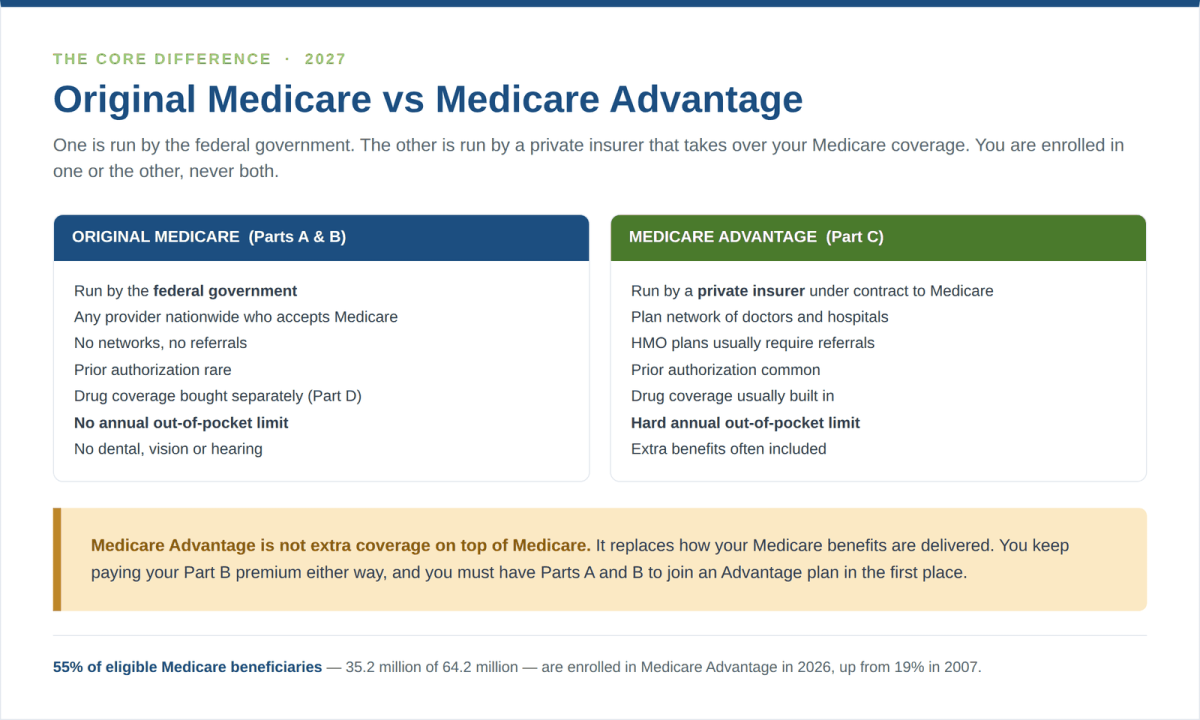
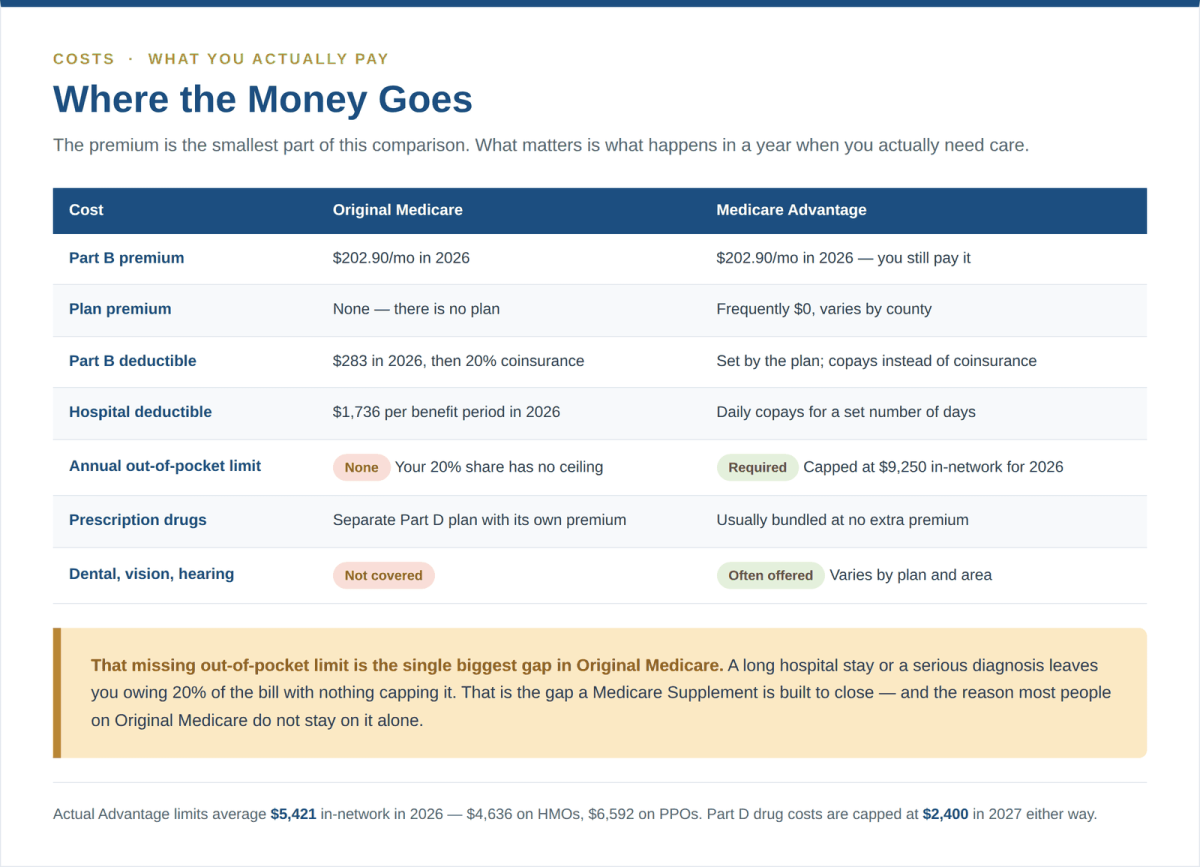
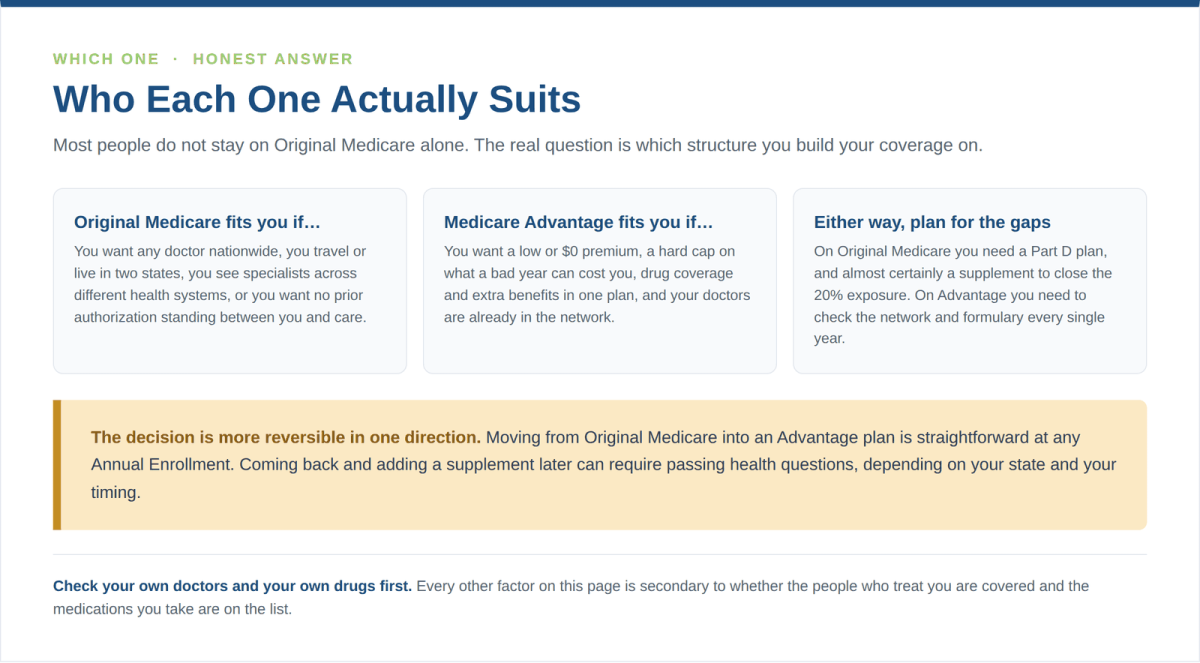
You want any doctor in the country without checking a list, you travel or split the year between two states, you see specialists across more than one health system, or you want nothing standing between a doctor’s recommendation and the care happening. It also suits people who would rather decide once than review a plan every autumn. Add a Part D plan for drugs, and seriously consider a supplement to close the 20% exposure.
Medicare Advantage tends to fit you if
A low or $0 plan premium matters to your budget, you want one card and one plan rather than three separate pieces, your doctors are already in a network, and you value a hard ceiling on what a bad year can cost. The extra benefits that often come attached — dental, vision, hearing — are real, though what is included varies by plan and by area.
Plan quality varies enormously between carriers, which is worth knowing before you judge Medicare Advantage as a category. Kaiser Medicare Advantage rates 4 stars or better on every plan it sells, while other carriers have most of their members in plans rated well below that. The structure is not the whole story — the carrier is.
Look harder before deciding if
You have a chronic condition, take expensive specialty medications, or receive care across several health systems. Those are precisely the situations where networks, prior authorization and formulary decisions carry the most weight, and where the cheaper monthly number can end up being the more expensive year.