➤ What is the best Medicare Advantage plan in California?
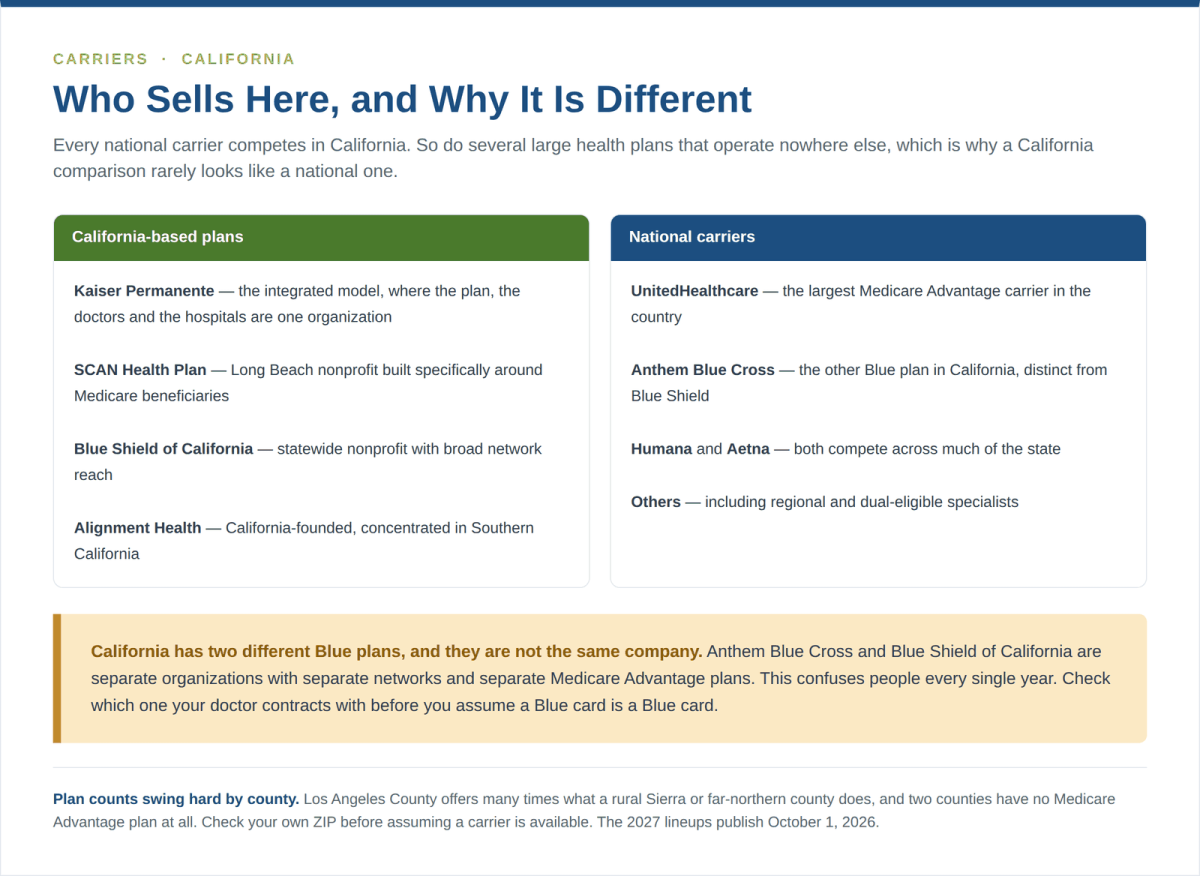
There is no single best plan in a state this large, and any page naming one is guessing at your circumstances. California has more than fifty counties with materially different plan lineups, plus several California-only carriers that do not compete everywhere in the state. Kaiser Permanente has consistently rated well on CMS quality measures and is a strong fit for people comfortable with an integrated system; SCAN Health Plan was built specifically around Medicare members; the national carriers offer broader geographic reach. The best plan for you is the one that covers your doctors, covers your prescriptions at a workable tier, and sets an out-of-pocket maximum you could absorb in a bad year.
➤ What company has the best Medicare Advantage plan for 2026?
On the most recent CMS star ratings, Kaiser Permanente placed at or near the top among large carriers on the share of members in 4-star-and-above plans, and it is widely available in California. But company-level averages are a blunt instrument. Ratings attach to individual contracts, so a highly rated carrier can offer a mediocre plan in your county and a lower-rated carrier can offer an excellent one. The 2027 ratings publish in October 2026 and could move these positions in either direction, so treat any company ranking as a starting filter rather than an answer.
➤ Which Medicare Advantage plans are 5 star?
CMS awards 5 stars to a small number of individual contracts each year, not to companies, and the list changes annually. A 5-star plan also carries a practical advantage worth knowing about: you can switch into one using a Special Enrollment Period at almost any point during the year, rather than waiting for Annual Enrollment. To find out whether a 5-star plan exists in your California county, check the 2027 ratings when they publish in October 2026 through Medicare’s Plan Finder, or see our guide to top rated Medicare Advantage plans.
➤ Why do people say to stay away from Medicare Advantage plans?
The criticisms are real and worth understanding rather than waving away. Medicare Advantage plans use networks, so your preferred doctor may not be covered. Many require prior authorization for procedures Original Medicare would simply pay for. Costs arrive as copays during a bad health year rather than as a predictable premium. And the decision is easier to make than to reverse — moving back to Original Medicare with a supplement later usually means medical underwriting, and California’s birthday rule does not change that. The counterargument is equally real: every Medicare Advantage plan caps your annual out-of-pocket spending, which Original Medicare on its own does not, and many carry no additional premium.
➤ How does the California birthday rule work?
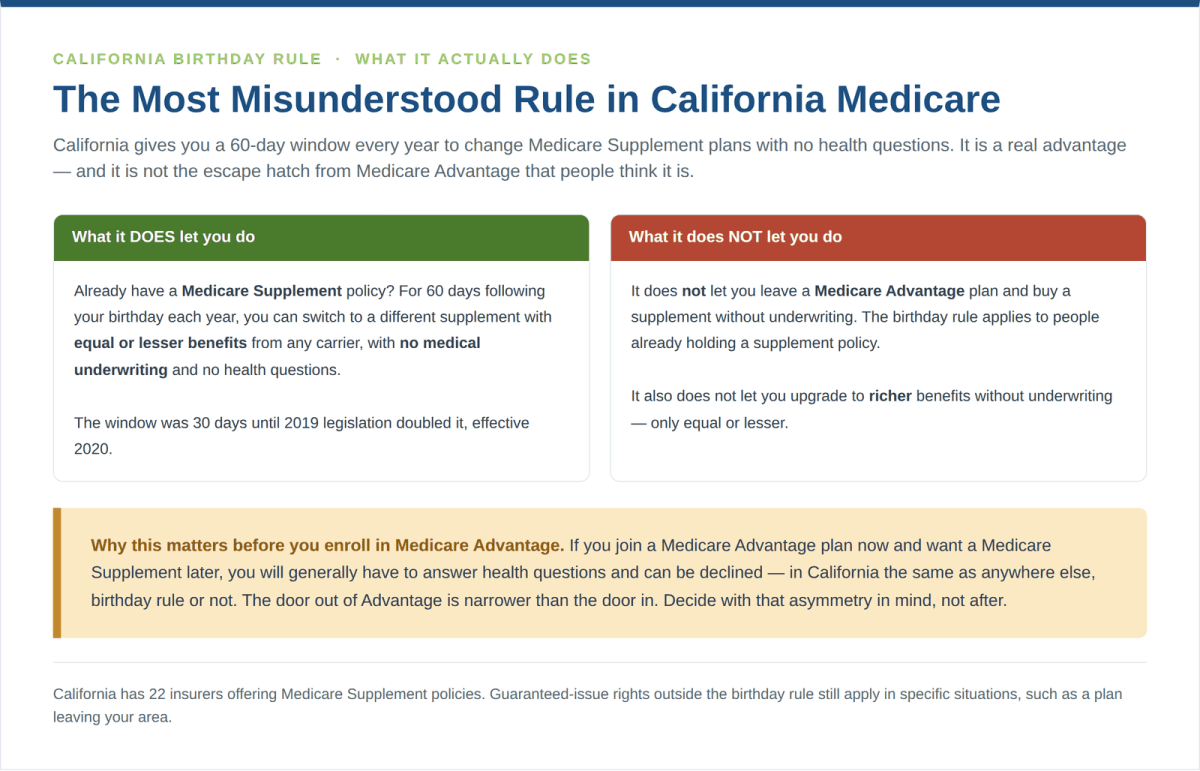
If you already hold a Medicare Supplement policy, California gives you a 60-day window each year following your birthday to switch to a different supplement with equal or lesser benefits, from any carrier, with no medical underwriting. The window was 30 days until 2019 legislation extended it, effective 2020. Two limits matter: it does not let you move up to richer benefits without underwriting, and it does not let you leave a Medicare Advantage plan for a supplement without underwriting. It is a supplement-to-supplement rule.
➤ Are Anthem Blue Cross and Blue Shield of California the same company?
No. They are two separate organizations, and California is one of the few states where both a Blue Cross and a Blue Shield plan operate independently. They have different Medicare Advantage plans, different provider networks and different costs. A practice that contracts with one may not contract with the other, so when you confirm coverage with your doctor’s office, name the specific plan rather than asking whether they take Blue.
➤ What is a Medi-Medi Plan in California?
A Medi-Medi Plan is California’s name for a Dual Eligible Special Needs Plan, a Medicare Advantage plan for people who qualify for both Medicare and Medi-Cal in which one organization manages both sets of benefits. California now only contracts with dual-eligible plans that have an affiliated Medi-Cal plan, and plans without one can no longer enroll new members. Availability is county-specific and has been expanding, so check what exists where you live. If you qualify, this is usually the first option to evaluate.
➤ How many Medicare Advantage plans are available in California?
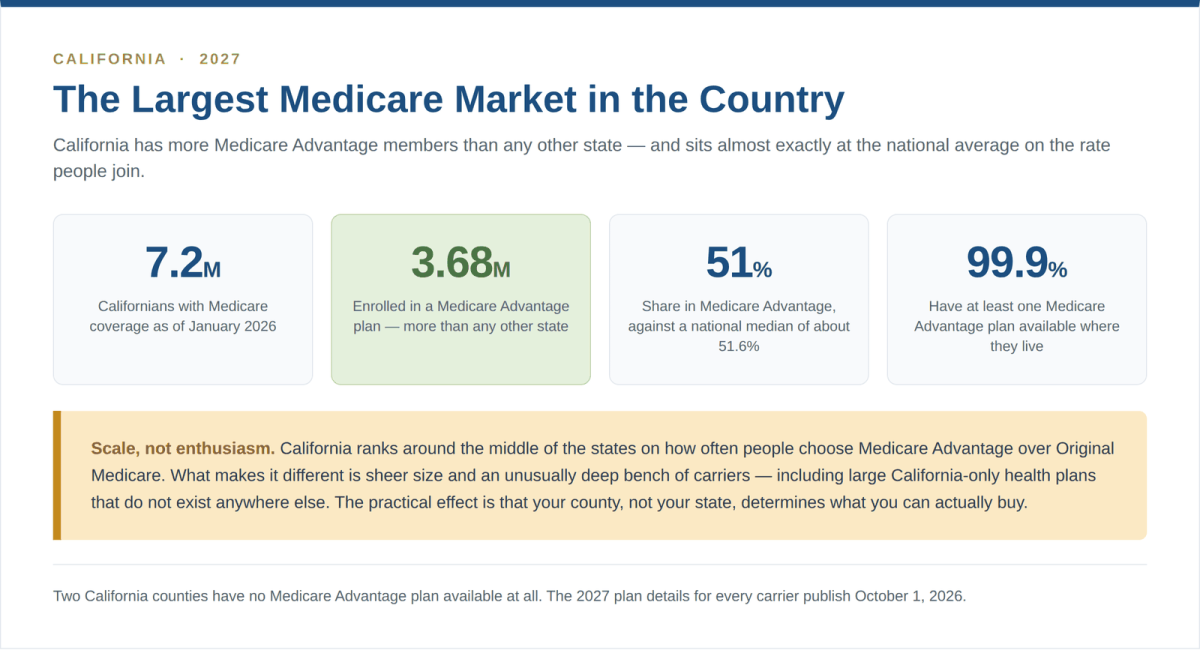
Statewide the number runs into the hundreds, but that figure is close to meaningless for any individual. What matters is your county, and California’s range is extreme: dense Southern California and Bay Area counties offer many times what rural Sierra and far-northern counties do, and two California counties have no Medicare Advantage plan available at all. Overall, 99.9% of California Medicare beneficiaries have at least one plan available where they live.
➤ When will 2027 California plan details be available?
Carriers publish 2027 plan details on October 1, 2026, two weeks before Annual Enrollment opens. Premiums, copays, networks, formularies and supplemental benefits are not final before that date, and several carriers have signalled reductions for 2027, so a plan available in your county this year may not return. Anything published about 2027 benefits ahead of October 1 should be treated as directional rather than confirmed.